9 min read · Last updated September 16, 2026
- A standard Business Owners Policy (BOP) automatically extends coverage to a new business location for exactly 30 days from the day you take possession, per the Insurance Services Office (ISO) Businessowners Coverage Form, form BP 00 03.
- The automatic extension caps a newly acquired building at $250,000 and everything inside it, equipment, inventory, and fixtures, at $100,000, regardless of the limits already on your policy’s declarations page.
- Coverage under the extension ends the moment any of three things happens first: 30 days pass, the policy itself expires, or you report the new location’s values to your insurer.
- Reporting late still costs you. Insurers bill added premium retroactive to the date you acquired the property, not the date you called.
A standard Business Owners Policy automatically covers a newly acquired or newly leased business location for up to 30 days, capped at $100,000 in business personal property and $250,000 per building, and that protection ends the moment 30 days pass, whether or not the owner ever calls to add the new location.
In this article
- What the automatic extension actually promises
- The two dollar caps that apply instead of your regular limits
- Three triggers that end the automatic extension
- Renata’s day 38 fire
- What to do the day you sign the lease
- Frequently asked questions
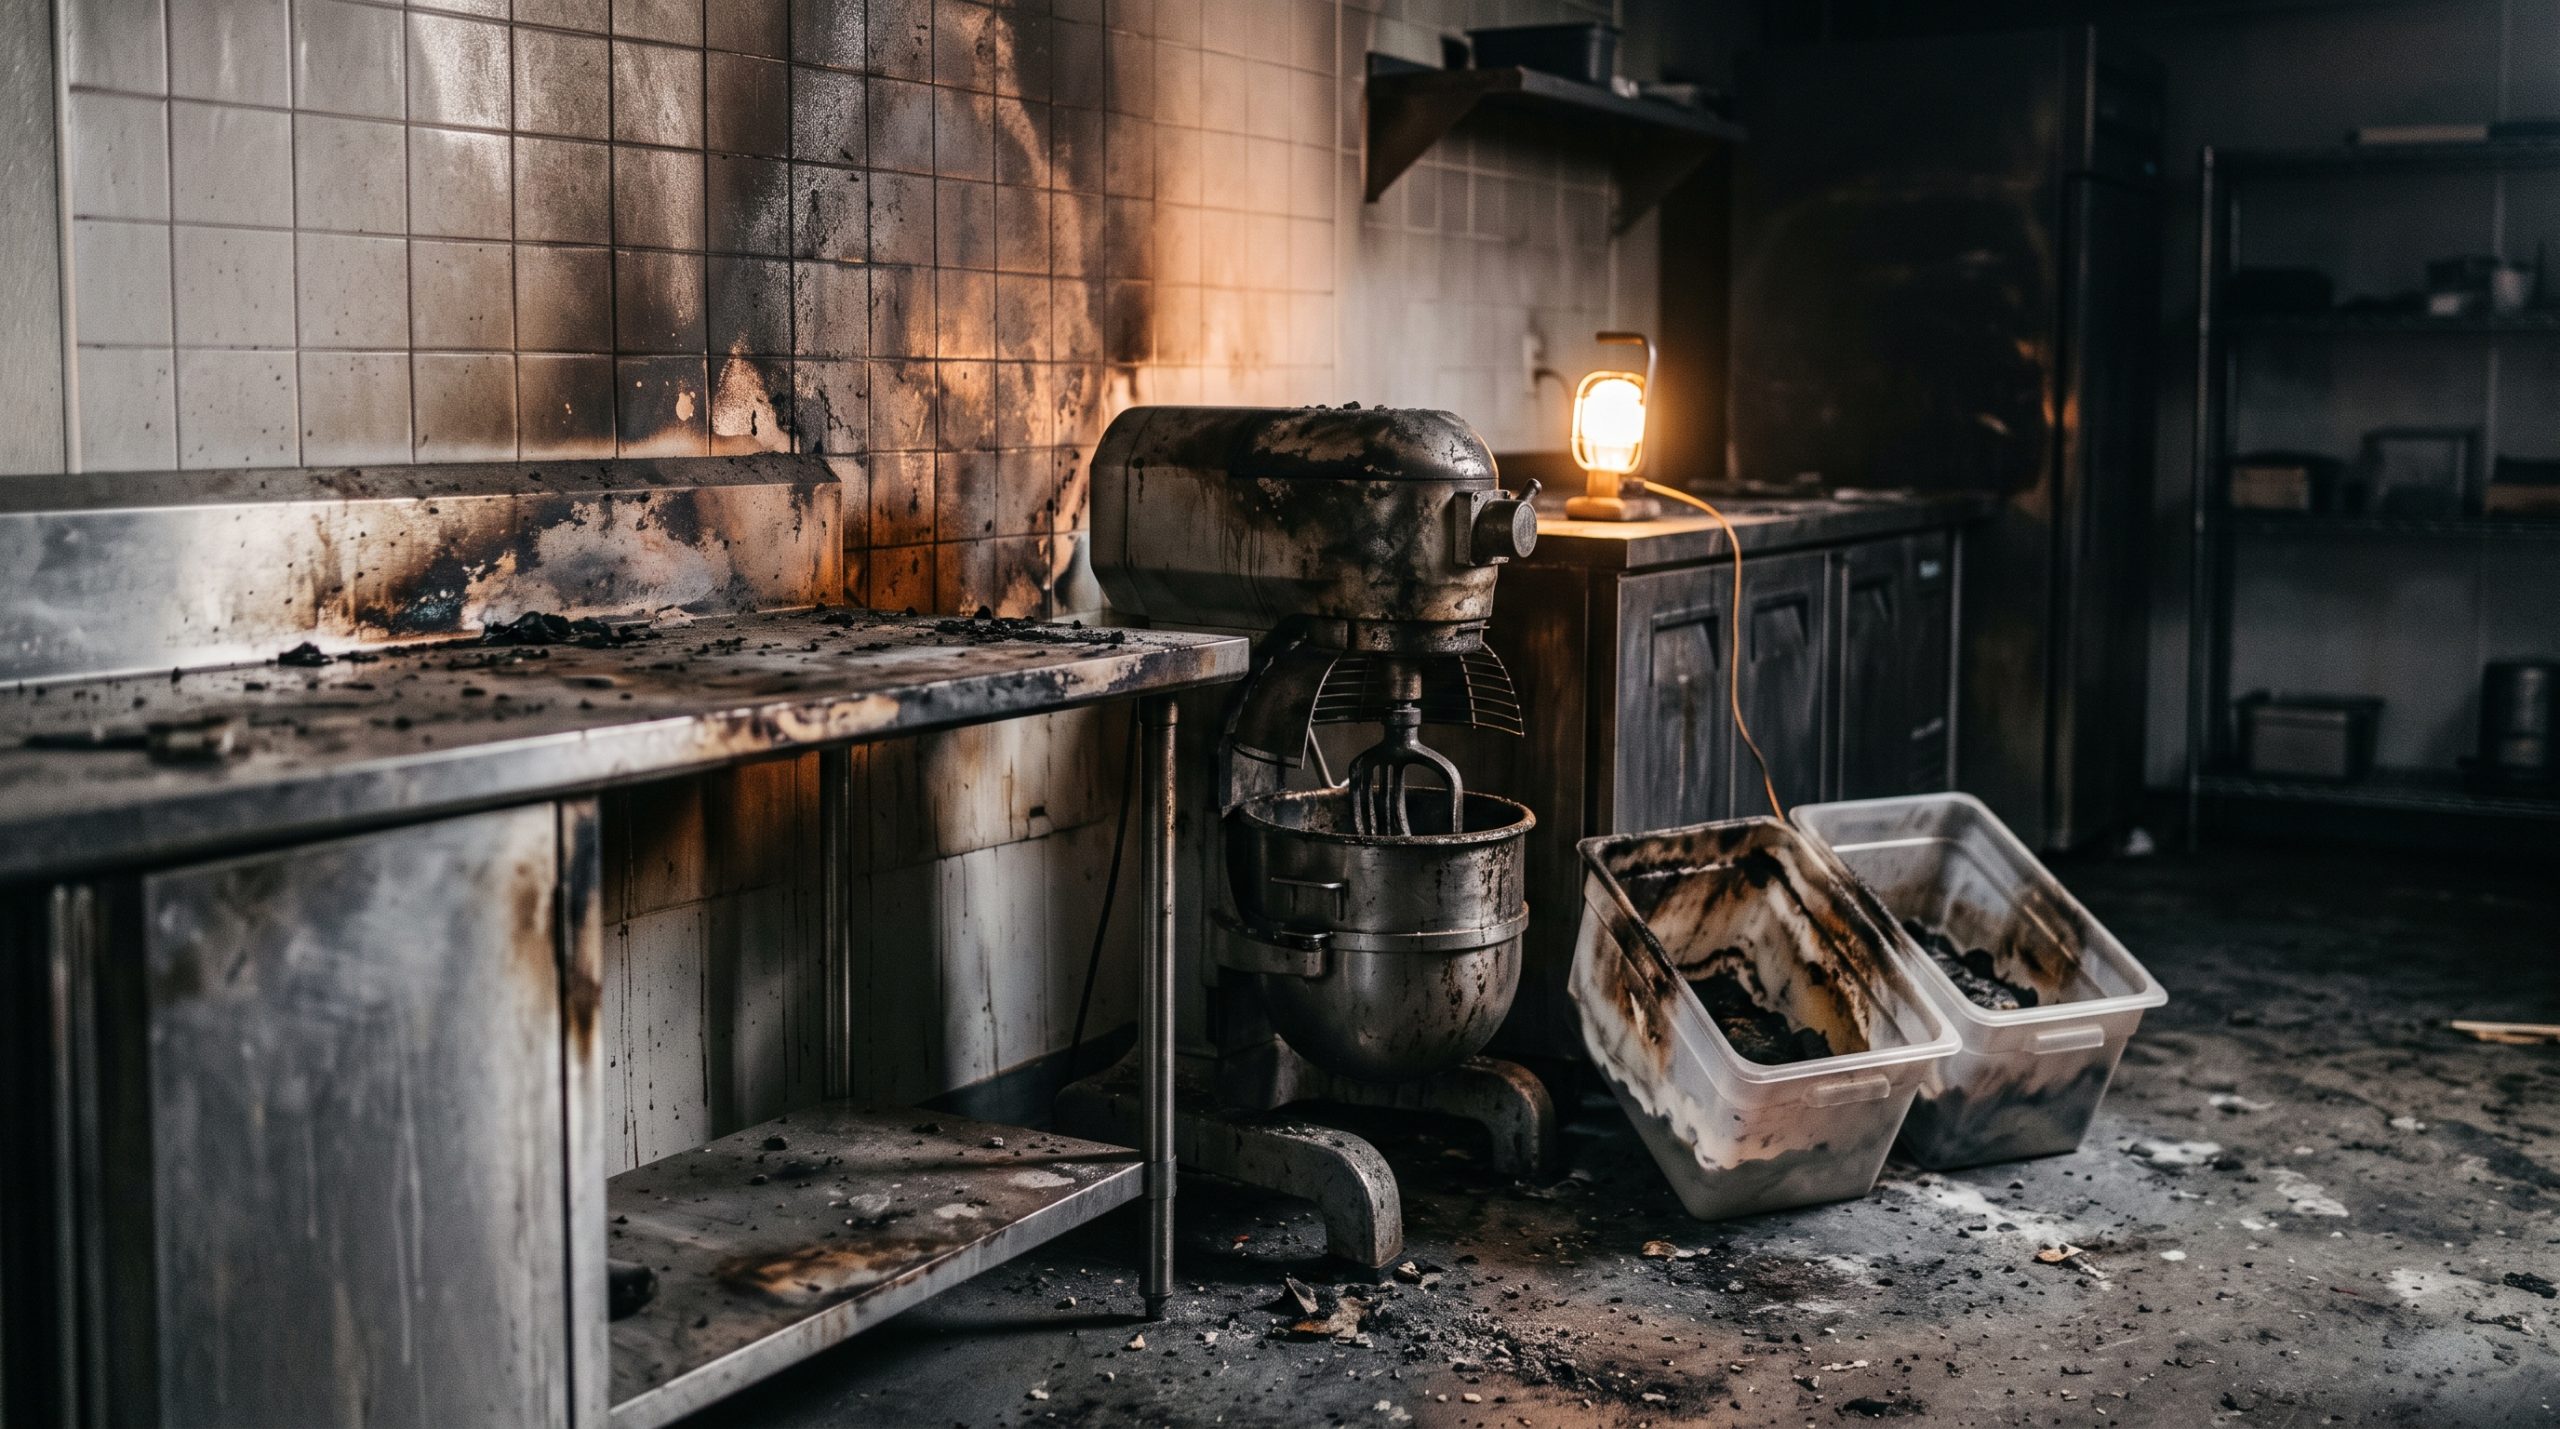
Renata Cabrera signed the lease on a second bakery kitchen on July 1, 2026, the same month her original shop hit its best sales on record. She moved in two commercial ovens, a $14,000 spiral mixer, and six weeks of flour and packaging inventory, then got busy hiring and training a crew to run the new space. She meant to call her agent about adding the address to her Business Owners Policy (BOP). She never got to it. On August 8, 38 days after she took possession, a grease fire in the new kitchen’s exhaust hood destroyed the mixer, both ovens, and $31,400 in inventory and packaging. Her policy paid nothing toward any of it.
What the automatic extension actually promises
A Business Owners Policy doesn’t require an owner to call in every new location the moment it happens. The standard ISO Businessowners Coverage Form, BP 00 03, builds in a grace period called the Newly Acquired Or Constructed Property extension. If the policy covers Business Personal Property, the form extends that insurance to “Business Personal Property, including such property that you newly acquire, at any location you acquire.” If the policy covers buildings, that same form extends coverage to “buildings you acquire at premises other than the one described,” as long as the new building is used similarly to the one already on the declarations, or as a warehouse.
That single sentence does a lot of work for an owner who leases, rather than buys, a second location. The Business Personal Property piece of the extension doesn’t require owning the building at all. It applies to the equipment, inventory, and fixtures at any location the business acquires, which is how insurance-industry analysis of this same policy language describes a newly leased kitchen, storefront, or warehouse qualifying the same way a purchased building does. Renata’s mixer and ovens qualified from the moment she moved them in. The catch is how long that protection actually lasts.
The two dollar caps that apply instead of your regular limits
The automatic extension doesn’t borrow the limits already sitting on Renata’s declarations page. It sets its own, smaller caps. Per the specimen BOP form and the same trade-publication analysis of it, the extension pays no more than $250,000 for a newly acquired or newly constructed building, and no more than $100,000 for business personal property at each new location. Those numbers apply no matter what her existing policy’s Business Personal Property limit says back at her original shop.
For a business opening something modest, like a bakery kitchen, a small retail annex, or a satellite office, $100,000 usually covers the loss outright. For a business opening something larger, the smaller of the two automatic caps can leave a real gap the moment it’s needed most. DIN’s overview of what a BOP does and doesn’t cover walks through several of these built-in ceilings, and the pattern repeats here: the automatic extension is built to bridge a short reporting gap, not to substitute for real, ongoing coverage on the new location.
Three triggers that end the automatic extension
The same BP 00 03 form spells out exactly when this temporary coverage stops applying, and it isn’t a single date. Coverage under the extension “will end when any of the following first occurs,” and one of those three triggers is that “30 days expire after you acquire the property or begin construction of that part of the building that would qualify as covered property.” The other two are the policy’s own expiration date, or the day the owner reports the new location’s values to the insurer. Whichever of the three happens first wins, and the clock never resets once it starts.
The 30-day trigger is the one owners misjudge most often, because it starts on the date of acquisition, not the date anyone gets around to making a phone call. The table below lines up all three triggers against what actually happened at Renata’s new kitchen.
| Trigger | What it means | Renata’s timeline |
|---|---|---|
| 30 days pass since acquiring the property or starting construction | The clock starts the day you take possession or break ground, not the day you call your agent | Started July 1, 2026. Expired July 31, 2026 |
| The policy itself expires | If your BOP renews before day 30, the extension ends with the old policy term regardless of the 30-day count | Not reached. Renata’s policy wasn’t due to renew until November 2026 |
| You report the new location’s values to the insurer | Regular policy limits take over once the insurer processes the report, and additional premium is billed back to the acquisition date | Never happened before the fire on August 8, 2026 |
Renata’s day 38 fire
Renata took possession of the new kitchen on July 1. Day 30 of the automatic extension fell on July 31. She hadn’t called her agent by then, and her BOP’s next renewal wasn’t due until November, so the policy itself hadn’t expired either. That left one live trigger standing: the calendar. The fire happened on August 8, 38 days after she signed the lease and eight days after her automatic extension had already lapsed on its own.
Renata’s loss, roughly $14,000 for the mixer, about $9,600 combined for the two ovens, and $31,400 in inventory and packaging, totaled close to $55,000. Every bit of that fell comfortably under the extension’s $100,000 cap. The cap was never the problem. The date was.
DIN’s coverage of a salon build-out that burned tells a version of this same clock from the other side. That owner reported her new build-out in time and still had her claim underpaid over a valuation dispute. Renata’s case is the harder version. She never crossed the reporting threshold at all, so there was no claim to underpay. Her insurer had no record connecting that address to her policy, and the automatic extension that would have covered the gap had already run out.
What to do the day you sign the lease
The fix costs nothing but a phone call, ideally made the same day the lease is signed or the keys change hands, not after the new location is stocked and running. Reporting early doesn’t waste money, either. Because the ISO form charges added premium retroactive to the date of acquisition regardless of when the report is filed, an owner who calls on day 25 pays the same back-dated premium as one who calls on day 2. The only thing that changes with early reporting is whether a loss during that window gets paid.
That added premium is landing at a moment when BOP renewals are already trending upward nationwide. The Ivans Index, which tracks small-business commercial insurance renewal rates, put BOP renewals up 6.16% in the second quarter of 2026, easing slightly from 6.74% in the first quarter. Reporting a new location promptly adds a real but usually modest increase on top of that renewal trend. Missing the 30-day window, then having a loss, adds a bill with no ceiling on it at all.
DIN’s look at a seasonal inventory sublimit covers a related version of this same lesson: the automatic protections built into a BOP are real, but they’re sized for a short gap, not for an owner who never circles back. Treat the day a new location opens as day one of a countdown, put it on a calendar, and call before day 30, not after it.
Frequently asked questions
Does a Business Owners Policy automatically cover a new business location?
Yes, for a limited time. The standard ISO Businessowners Coverage Form (BP 00 03) automatically extends coverage to a newly acquired or newly leased location for up to 30 days, capped at $100,000 for business personal property and $250,000 for a newly acquired building, before the owner reports the location to the insurer.
How long do I have to report a new business location to my insurer?
The automatic extension lasts 30 days from the date you acquire the property or begin construction, or until your policy expires or you report the location’s values, whichever comes first. Reporting sooner doesn’t cost extra, since insurers bill added premium back to the acquisition date regardless of when you call.
What happens if I don’t report a new location within 30 days?
Once the automatic extension ends, whether by the 30-day deadline, policy expiration, or a values report, a loss at that unreported location isn’t covered at a reduced amount. Nothing about the automatic extension carries over once one of those three triggers occurs.
Does a BOP’s newly acquired property extension cover a leased location?
For business personal property, the ISO language applies to equipment and inventory at “any location you acquire,” which doesn’t require owning the building, so a newly leased space typically qualifies the same way a purchased one does. The building extension itself is written specifically for buildings the owner acquires.
Will my insurer charge extra premium for a newly reported location?
Yes. Once a new location is reported, most Businessowners policies charge additional premium retroactive to the date the property was acquired or construction began, not the date it was reported. That charge lands on top of BOP renewal trends generally, which pushed rates up 6.16% nationwide in the second quarter of 2026.
Renata’s second kitchen is back open now, rebuilt out of pocket because the automatic extension had already run out before the fire ever started. The extension itself did exactly what it was built to do: buy 30 days, not indefinite protection. For any BOP holder opening a second address this year, that countdown starts the day the keys change hands, whether or not anyone remembers to make the call.
Opening a second location? Compare business insurance before your 30-day window closes
See business insurance options built for owners adding a new address, before the automatic $100,000 extension runs out.
Compare Business Insurance Options