8 min read · Last updated October 7, 2026
- A dwelling-damage claim check is made out jointly to the homeowner and the mortgage servicer because of the mortgagee clause written into every homeowners policy, not because of a processing error.
- On a current loan backed by Fannie Mae, the servicer can release up to the greater of $40,000 or 33% of the insurance proceeds as an initial disbursement, holding the rest for inspection-based draws, per Fannie Mae’s own Servicing Guide.
- Wells Fargo’s own published claims process pays out in roughly three stages: after paperwork is filed, after an inspection confirms repairs are about 25% or more complete, and after a final completion inspection.
- California law caps what a contractor can demand as a deposit at $1,000 or 10% of the contract price, whichever is less, which matters when the servicer hasn’t released enough to cover what a contractor is asking for upfront.
A homeowners insurance check for dwelling damage comes as a two-party payment, naming the mortgage servicer alongside the homeowner. That’s because of the mortgagee clause written into the policy itself, not a bank error. The servicer deposits that money into a loss draft account.
It releases the funds in stages tied to its own inspection schedule, on a timeline set by the loan’s investor guidelines rather than by the insurance company.
In this article
- Why her signature alone wasn’t enough: the mortgagee clause on a two-party insurance check
- Where does the $41,000 actually sit?
- The dollar line that decides how fast the money moves
- When the contractor wants money before the servicer sends it
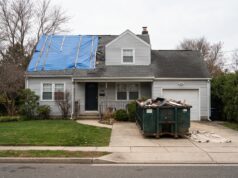
A $41,000 insurance check for roof damage arrived with two names on it, and only one of them had ever set foot on the roof. Rosalind Ferreira’s insurer approved the payout after a spring hailstorm tore through her Charlotte, North Carolina subdivision, but the company that services her mortgage was named on the check too.
Two weeks after the claim was approved, the check arrived in the mail. Her name was on it, and so was her mortgage servicer’s.
Why Her Signature Alone Wasn’t Enough: the Mortgagee Clause on a Two-Party Insurance Check
Every standard homeowners policy carries a provision insurers call the standard mortgage clause. Depending on the state form it traces back to, it’s sometimes labeled the union mortgage clause or the New York standard mortgage clause. It names the lender, or whoever now services the loan, as a party entitled to payment “as interests may appear.”
Lenders shorthand that phrase as ATIMA (As Their Interests May Appear).
Chase explains it plainly: the clause “protects the lender’s financial interest in the property.” ATIMA language “ensures coverage applies to any lender or entity with a financial stake in the property at the time of a claim.” That protection continues even after the loan is sold to a new servicer.
The reason the clause exists is more specific than simple caution. According to the International Risk Management Institute’s (IRMI) analysis of the mortgagee clause, it functions as “a contract within a contract, one being between the insurer and the debtor ‘home owner’ and the other between the insurer and the lender.” That second, independent contract survives even when the homeowner’s own claim wouldn’t.
The group’s own example is stark: “even if a borrower burns or otherwise destroys her own home, thereby negating the possibilities of an insurance recovery, a lender, by complying with policy conditions, can still collect insurance proceeds.” A vacancy violation, a lapsed policy condition, even arson by the owner, none of it automatically erases the lender’s right to be paid.
Putting both names on the check from the start is how the insurer honors both contracts with a single payment instead of litigating who gets what later.
Where does the $41,000 actually sit?
Once Rosalind endorses the check and sends it to her servicer, the money doesn’t go into her checking account. It goes into what the industry calls a loss draft account, a holding account the servicer controls until repairs are verified. Wells Fargo’s own published claims-and-repairs process describes the standard pattern for monitored repairs in three stages.
An initial release comes “after the initial documentation is received.” A second release follows “when repairs are 25% or more complete, and a progress inspection has been completed.” A final release comes “when repairs are finished and have been inspected.”
Minor damage can be endorsed over to the homeowner in full, Wells Fargo notes. But the company doesn’t define a specific dollar line where that switch happens, because that line is set loan by loan.
For loans backed by Fannie Mae, there actually is a published number. Fannie Mae’s Servicing Guide lays out exactly how much a servicer is permitted to hand over before any inspection happens at all.
The dollar line that decides how fast the money moves
Fannie Mae’s Servicing Guide, chapter B-5-01 on insured loss events, gives servicers two different tracks depending on whether the loan is current. For a loan that is current or less than 31 days delinquent, a servicer is authorized to “release an initial disbursement of insurance loss proceeds up to the greater of $40,000; 33% of the insurance loss proceeds; or the amount by which the release funds exceed the sum of the UPB [the loan’s Unpaid Principal Balance], accrued interest, and advances on the mortgage loan.” On Rosalind’s loan, the third condition doesn’t come into play.
Thirty-three percent of her $41,000 claim works out to roughly $13,530, so the $40,000 figure is the one that controls for her. Her servicer has the authority to release nearly the entire claim, almost $40,000 of it, as a single upfront disbursement. It holds back only around $1,000 until a completion inspection closes the file.
For a loan that’s already 31 or more days delinquent, the same guide authorizes a smaller, more conservative initial release instead, well short of a near-full disbursement.
That $40,000 figure is a ceiling on what a servicer is allowed to release without extra approval, not a rule requiring it to release that much. A servicer can still choose the slower, three-draw pattern Wells Fargo describes, regardless of what Fannie Mae’s guide would technically permit. The real-world schedule below blends both published sources into the shape most claim files actually follow.
| Draw | What releases it | How much typically moves | Published source |
|---|---|---|---|
| Initial disbursement | Signed repair agreement and contractor estimate filed with the servicer | Up to the greater of $40,000 or 33% of total proceeds, on a current loan | Fannie Mae Servicing Guide, B-5-01 |
| Progress draw | On-site inspection confirms repairs are roughly 25% or more complete | A further portion of the held-back balance | Wells Fargo’s published claims-and-repairs process |
| Final draw | Completion inspection confirms the finished work matches the approved scope | Remaining balance released in full | Wells Fargo’s published claims-and-repairs process |
| Delinquent-loan track | Loan is 31 or more days past due when the insurer pays | A smaller, capped initial release instead of the current-loan amount | Fannie Mae Servicing Guide, B-5-01 |
The claim amount that’s actually withheld is a separate question from how the insurer calculated the payout in the first place. A policy settled on an actual cash value basis holds back depreciation the homeowner can only recover once the repair is finished. That’s a different pot of money than anything sitting in a loss draft account.
Roof claims specifically are also where insurers are leaning hardest on aerial and satellite imagery to flag roof condition long before a storm ever hits. That’s a separate fight, one that happens at renewal rather than at claim time.
When the contractor wants money before the servicer sends it
The gap between what a contractor wants upfront and what a servicer has actually released is where most homeowners get stuck. A roofer who wants a large deposit before ordering materials is asking for money the loss draft account may not be holding yet. That’s especially true if the servicer chose the slower, three-draw pattern over the faster disbursement its investor guidelines would otherwise allow.
State law puts a real ceiling on this in at least one major state. California’s Business and Professions Code caps a contractor’s deposit on a home improvement contract at “one thousand dollars ($1,000) or 10 percent of the contract amount, whichever amount is less,” per the statute itself.
On a $41,000 roof job like Rosalind’s, 10% would be $4,100, but the law uses whichever figure is lower. So the legal cap stays at $1,000 regardless of the contract’s size.
In a state with a similar rule, a homeowner facing a contractor demanding more than that cap has grounds to push back. The homeowner shouldn’t pay anything beyond the first draw the servicer has already released.
The practical fix is sequencing the contract to match the draws instead of fighting them. A written agreement that ties each payment to a completed milestone (materials delivered, framing done, final inspection passed) mirrors the exact structure the servicer is already using to release funds. That keeps a homeowner from paying out of pocket for work the loss draft account was always going to cover anyway.
Frequently asked questions
Why is my homeowners insurance check made out to my mortgage company? Your policy’s mortgagee clause entitles your lender, or whoever services the loan, to be paid alongside you on any dwelling-damage claim. Insurers put both names on one check rather than issuing two separate payments, which is why the check can’t be deposited without the servicer’s endorsement too.
What is a loss draft account? It’s the holding account a mortgage servicer deposits an endorsed insurance check into after a dwelling-damage claim. The servicer controls the account and releases money in draws tied to repair progress, rather than handing the full balance to the homeowner at once.
How much can a servicer release before an inspection? On a current loan backed by Fannie Mae, the servicer can release up to the greater of $40,000 or 33% of the total proceeds as an initial disbursement. Above that, remaining funds are typically held for progress and completion inspections before the rest is released.
Can I just deposit the insurance check myself? No. Because the servicer is a named payee under the mortgagee clause, a two-party check generally requires its endorsement before any bank will accept it. That’s true even though the claim was approved in your name.
What can I do if my contractor wants a deposit before the servicer pays? Check your state’s contractor deposit rules first. California caps deposits at $1,000 or 10% of the contract price, whichever is less. Beyond that, write the contract so each payment matches a completed milestone, which lines up with how the servicer is already planning to release funds.
Your Next Roof Claim Shouldn’t Depend on Guessing Your Servicer’s Draw Schedule
Compare homeowners insurance options and see what coverage actually looks like before the next storm forces the question.
Compare Homeowners Insurance