7 min read · Last updated October 14, 2026
- A standard renters policy caps personal property “located in a storage facility” at 10% of your Coverage C limit, or $1,000, whichever is greater, per a renters policy form filed with the Oklahoma Insurance Department.
- A $40,000 personal property limit produces only a $4,000 storage-unit limit, since 10% of $40,000 exceeds the $1,000 floor.
- Two narrow exceptions remove the cap: property moved out because your actual apartment is being repaired and is unfit to live in, and property at a newly acquired home for the first 30 days.
- A self-storage facility’s own tenant protection plan is a separate product with its own limits and is not a substitute for checking your renters policy’s sublimit first.
A standard renters policy caps property kept in a storage unit at 10% of your Coverage C personal property limit, or $1,000, whichever is greater, with two narrow exceptions for property displaced by a home repair or moved to a brand-new residence in the first 30 days after you start moving in.
In this article
- The renters insurance storage unit coverage limit, explained
- Run the math against your own declarations page
- What a self-storage facility’s own insurance does and doesn’t fix
- Frequently asked questions
Renters insurance follows your belongings into a self-storage unit, but at a fraction of their value. A consumer guide from Wisconsin’s Office of the Commissioner of Insurance confirms that a standard policy covers belongings “destroyed or damaged away from your home,” subject to the policy’s own “terms, conditions, and limits.” The standard limit itself is 10% of your personal property coverage, or $1,000, whichever is greater, and most people never check that number until after a loss.
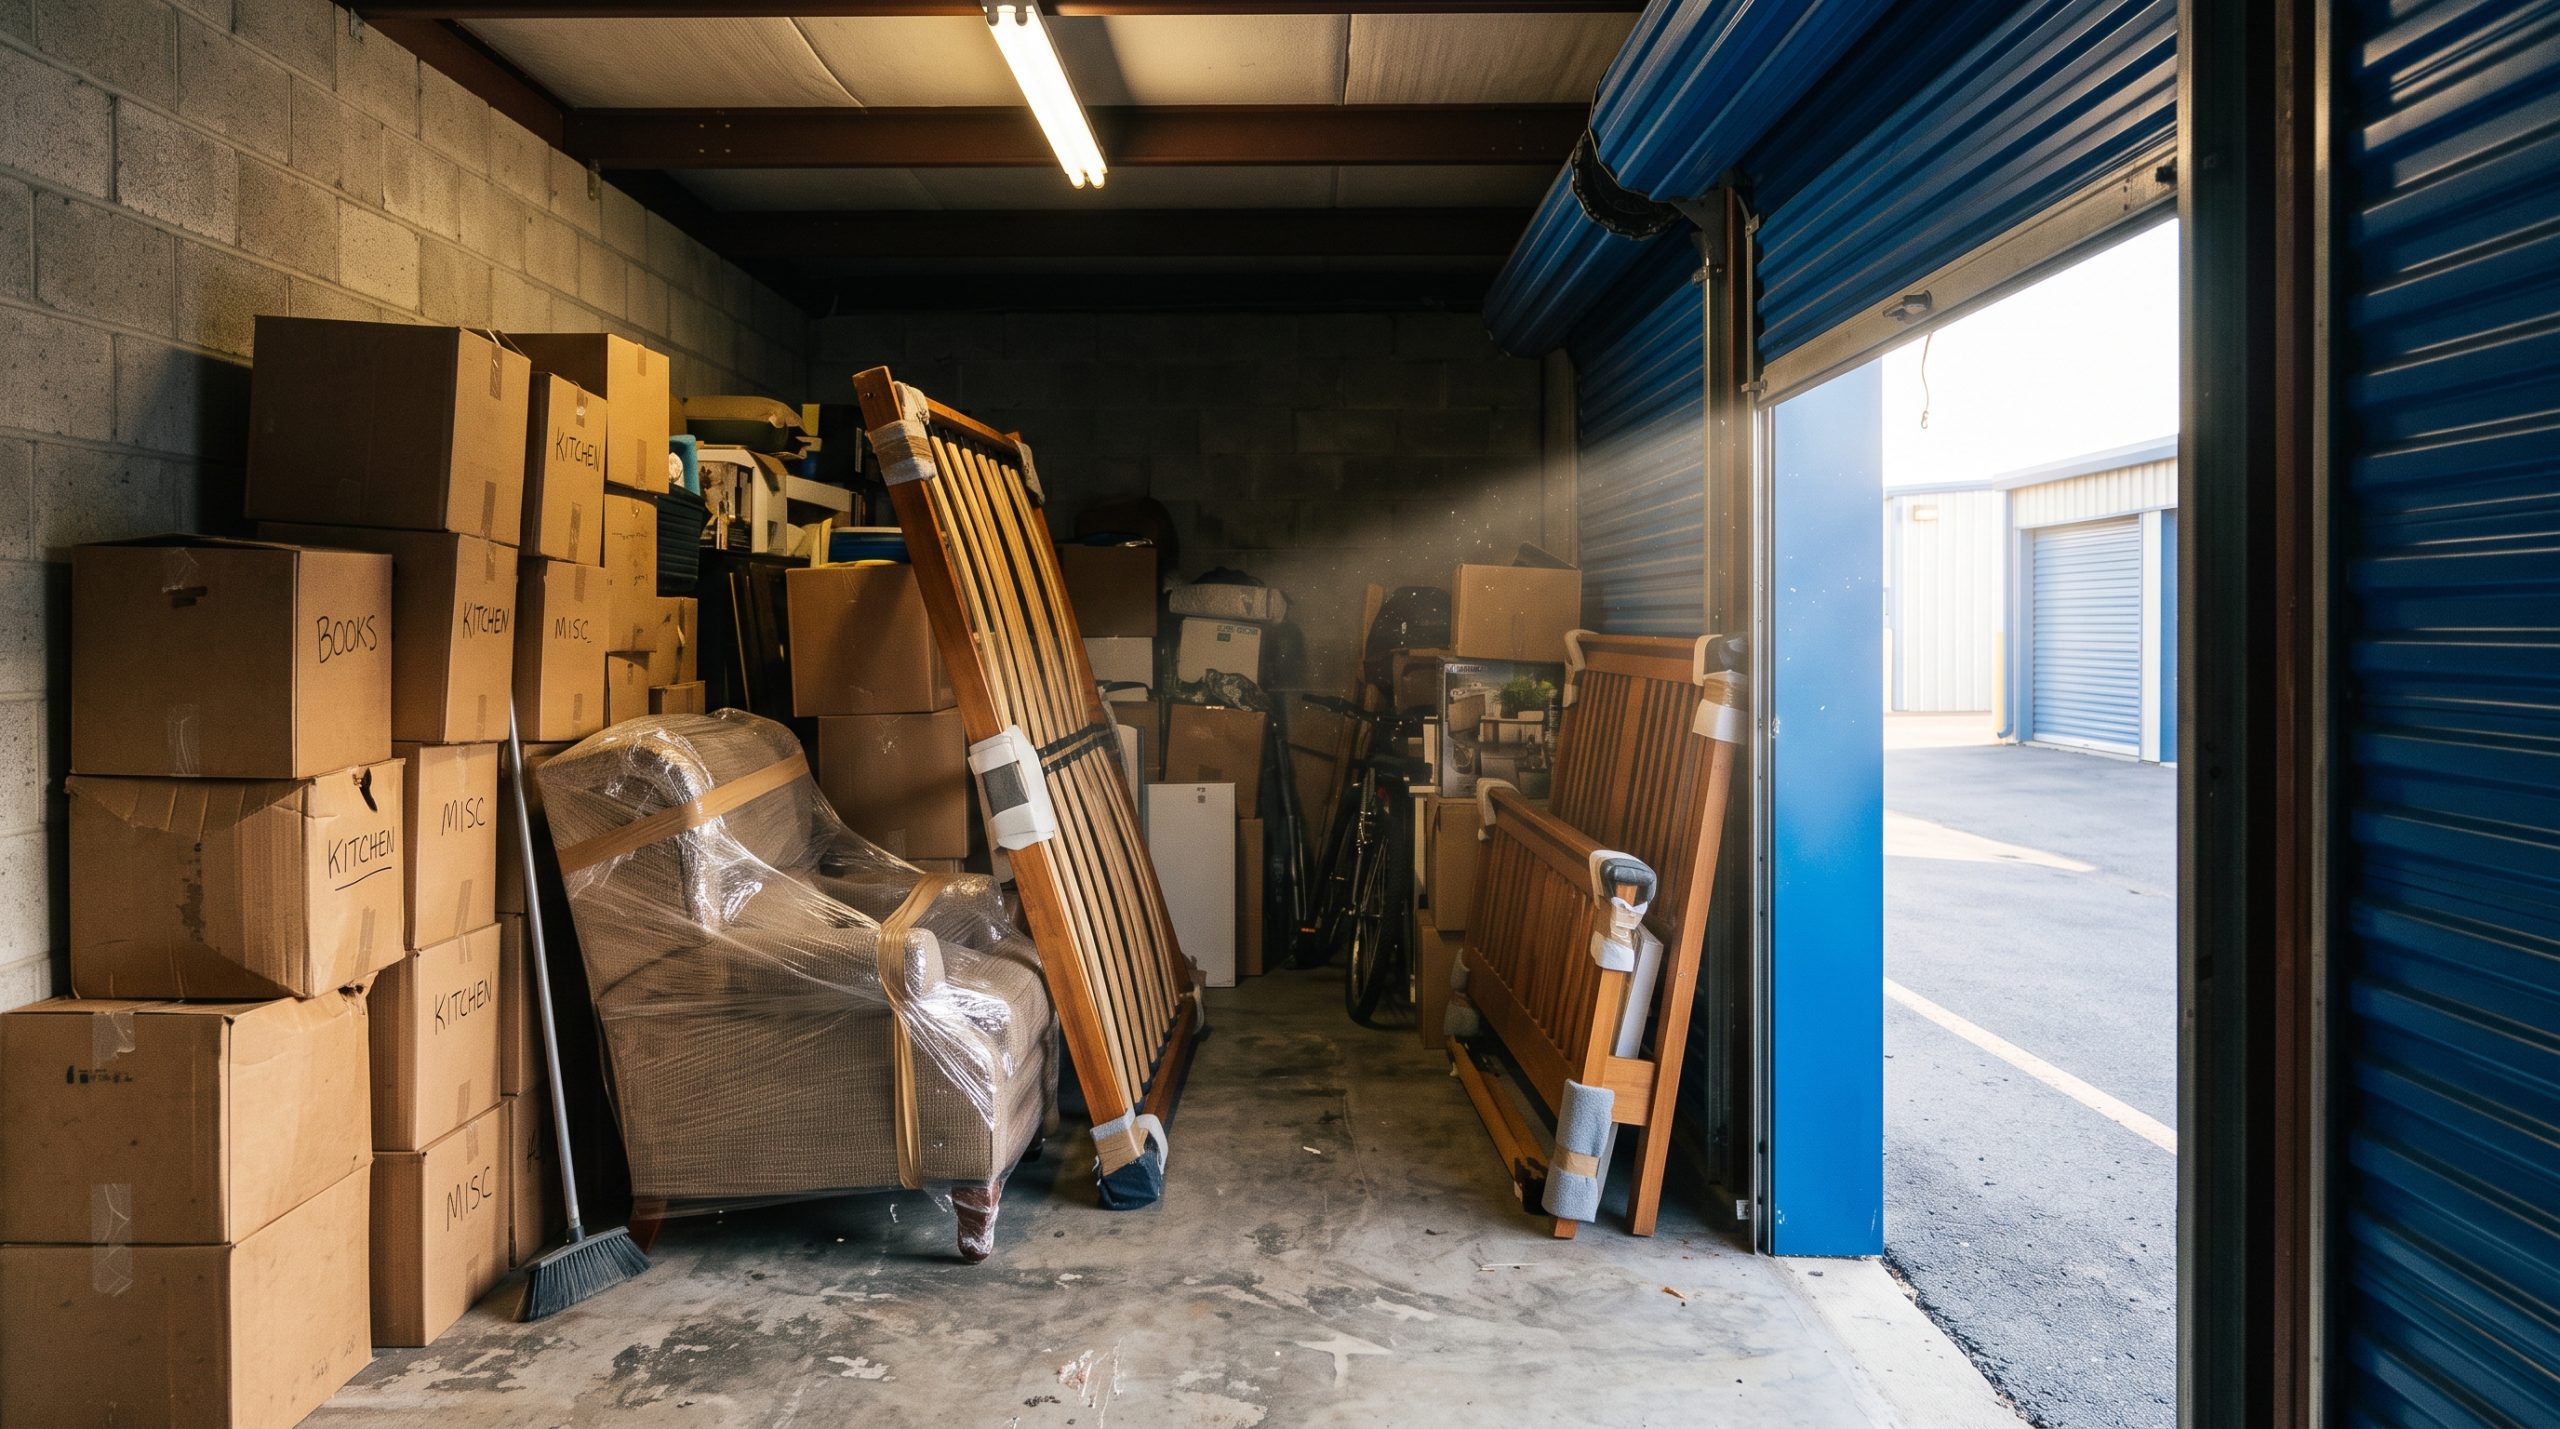
A $13,500 gap was sitting inside Jin-Ho Baek’s renters policy, and a fire in a Sacramento self-storage facility is what exposed it this past spring. He had put $17,500 of furniture and electronics into the unit for four months during a move between apartments, the same kind of move that leaves a mover’s own released-value limit this thin on the day the truck is loaded. A unit two doors down caught fire, and the blaze spread before anyone could stop it.
His renters policy carried a $40,000 personal property limit, which he had assumed meant full replacement. The adjuster explained the storage-facility sublimit instead, and the check came to $4,000 rather than the $17,500 he had actually lost.
The renters insurance storage unit coverage limit, explained
A renters policy form filed with the Oklahoma Insurance Department, underwritten by American Strategic Insurance (ASI), states the limit in plain terms: the insurer covers personal property “located in a storage facility or that is usually located at an insured’s residence that is not the ‘residence premises’ listed in this policy for up to 10% of the limit of liability for Coverage C, or $1,000, whichever is greater.”
Coverage C is the policy’s personal property section, the number on your declarations page that sets what your belongings are insured for inside your own apartment. The storage-unit limit is a percentage of that same number, not a separate pot of money layered on top of it.
Insurers write the sublimit this way because a storage unit sits outside anything the insurer can reasonably verify. At your actual apartment, an adjuster can inspect the space, match furniture to receipts, and confirm the loss matches what a typical unit of that size would hold.
A storage unit several miles away, rented under a different address, offers none of that. The sublimit exists to cap the insurer’s exposure to a claim it has no practical way to size up in advance, not to punish renters for storing their own belongings.
The same form sets two exceptions where the 10% cap does not apply. Property moved out because your actual apartment “is being repaired, renovated or rebuilt and is unfit to live in or store property in” keeps its full coverage. Property at a newly acquired home keeps full coverage for the first 30 days after you start moving in.
Neither exception covers an ordinary move, a downsizing, or simply running out of closet space, which is the reason most people actually rent a storage unit.
Both exceptions are narrower than they sound. The repair exception only applies while your actual apartment is genuinely unfit to live in, not while you’re simply decluttering or staging it for a new roommate.
The 30-day new-residence window starts the moment you begin moving property in, not the day you sign the lease, and it ends on day 30 regardless of how long the whole move actually takes. A renter who starts moving in gradually over six weeks loses the full-coverage exception on items moved after that first month closes, even though the move itself isn’t finished.
Run the math against your own declarations page
The gap scales with how much you store, not just whether you store anything at all, and it moves with your policy’s limit rather than with how large your actual storage unit is. The table below shows how the 10% rule plays out at three common Coverage C limits.
| Coverage C limit (at home) | Storage-unit limit (10%, or $1,000 floor) | Stored property value that exceeds it |
|---|---|---|
| $15,000 | $1,500 | Anything over $1,500 |
| $40,000 | $4,000 | Anything over $4,000 |
| $75,000 | $7,500 | Anything over $7,500 |
| Best for | Anyone with more than one storage unit’s worth of value sitting at or near the 10% line | |
Jin-Ho’s $40,000 Coverage C limit put his real storage-unit ceiling at $4,000. The $17,500 he actually had in the unit was never close to covered, and nothing about his declarations page said so directly. The number only exists inside the policy’s own definitions section, not on the summary page most renters actually read.
What a self-storage facility’s own insurance does and doesn’t fix
Most self-storage facilities sell their own tenant protection plan at move-in, and many renters assume signing up solves the problem the renters policy sublimit creates. It doesn’t automatically. A facility’s own plan is a separate product with its own coverage limits and its own exclusions, and the two policies do not combine into one larger number.
Facility-sold plans commonly cap out in the low thousands of dollars per unit, well below what a studio apartment’s worth of furniture and electronics actually costs to replace. Some also require a purchase receipt for every item claimed, which renters rarely keep for furniture bought years earlier or received as a gift. A renter who stacks a facility plan on top of an unchecked renters-policy sublimit can still end up with two policies, neither of which covers the full value in the unit.
The more reliable fix is a scheduled personal property endorsement added to your own renters policy, which raises the limit for specific high-value items you name and value in advance, the same type of endorsement that closes the gap on a quietly capped jewelry claim. For a general increase to the whole storage-unit sublimit rather than specific items, ask your insurer directly whether that endorsement exists on your policy form, since not every carrier offers it the same way.
Frequently asked questions
Does the 10% storage-unit limit apply to a basement storage cage in my own apartment building?
It depends on how your policy defines “residence premises.” A storage cage inside your own building and under your own unit number is typically treated as part of your residence; a facility across town, or a shared basement your lease doesn’t name, is more likely to fall under the away-from-home limit. Check with your insurer directly rather than assume.
If I raise my Coverage C limit overall, does my storage-unit coverage go up automatically?
Yes. Since the storage sublimit is calculated as 10% of your Coverage C limit, raising Coverage C raises the storage-unit ceiling proportionally, with no separate endorsement required for that part.
Does the storage-unit limit apply to theft as well as fire?
Yes. The 10% cap applies to the dollar amount paid for a covered loss in storage, regardless of whether the cause was fire, theft, water damage, or another named peril your policy covers.
Is a storage unit rented under my own name but used by a family member still subject to my renters policy’s limit?
Generally only property you own, or that a resident of your household owns, is covered under your policy at all. Property belonging to someone outside your household, even if they use your storage unit, usually needs its own coverage.
Should I just buy a bigger Coverage C limit instead of a separate endorsement?
It depends on how much you store and for how long. A modest permanent increase to Coverage C raises your storage-unit ceiling and your at-home coverage together; a scheduled endorsement is usually cheaper if the issue is a handful of specific high-value items rather than your whole stored inventory.
Check your renters policy’s Coverage C limit before your next move
Compare renters insurance options and see what it costs to raise your storage-unit coverage.
Compare Renters Insurance Quotes