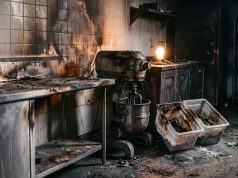
Wei opened a 4,000 square foot Asian fusion restaurant in Boston in 2018. The two-story brick building he owned outright was insured for $1 million, the figure his agent originally suggested at policy inception. In March 2024, a fryer fire spread to the duct system and damaged about $200,000 of structural and equipment value. When the carrier’s adjuster sent the settlement letter six weeks later, the check was for $147,000, not $200,000. The difference was the coinsurance penalty. Wei’s $1 million policy on a building now worth $1.7 million in replacement cost violated the 80 percent coinsurance clause buried on page nine of his commercial property policy. He was carrying 73 percent of the required coverage, and the carrier reduced his partial-loss claim by the same proportion.
What coinsurance actually requires
Most commercial property policies include a coinsurance clause set at 80, 90, or 100 percent of the building’s replacement cost value. The clause is a contractual requirement that the insured carry enough coverage to share the risk with the carrier. If the limit on the policy is below the required percentage at the time of loss, the carrier reduces the partial-loss payment by the same ratio of underinsurance.
The formula is simple: multiply the loss by the limit carried divided by the limit required. On Wei’s claim, that was $200,000 times ($1,000,000 divided by $1,360,000), which equals $147,059. The deductible came off after that calculation, not before.
Total losses are paid up to the policy limit regardless of the coinsurance clause. The penalty applies only to partial losses, which is what most commercial property claims are. Industry data from the Insurance Information Institute shows that fewer than 5 percent of commercial property claims involve a total loss. The coinsurance penalty is the rule, not the exception.
On a $200,000 loss, you’d be paid $147,059
That’s $52,941 less than the loss itself — the coinsurance penalty.
This shows the coinsurance math only. Your deductible is subtracted after this calculation, and a total loss is paid up to your policy limit regardless of coinsurance.