

Your Insurer Called a Slow Leak ‘Gradual Seepage’ and Denied the Claim. Here’s How...
Homeowners policies cover sudden, accidental water damage but exclude gradual seepage that builds over time. The difference decides whether your claim is paid, and an adjuster can read the age of a leak in the walls.
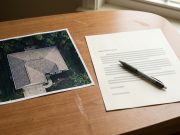
She Paid $16,400 for a New Roof. Her Nonrenewal Notice Cited a Photo Taken...
A homeowner's nonrenewal notice cited an aerial roof photo taken more than a year before she replaced the roof. Here is what these images can and cannot prove, and the dispute rights already on the books in several states.

A Dog-Bite Claim Averaged $65,450 in 2025. A Breed Exclusion Means You Pay All...
Your homeowners policy usually covers a dog bite up to the liability limit. A breed-exclusion clause can quietly strip that coverage from your specific dog first.
When the Condo Board’s Deductible Becomes Your $15,000 Bill
A windstorm hit her condo building's roof, and the association's board legally passed the master policy's deductible straight to the owners. Here's why her insurance barely covered it.

Personal Property Sublimits: Why Your $250,000 Homeowners Policy Pays Only $1,500 for Stolen Jewelry
A burglary cleaned out $9,200 in jewelry from Lauren Castillo's bedroom dresser. Her $250,000 homeowners policy paid only $1,500 because of a sublimit she had never read.

How to Compare Homeowners Insurance Policies
Owning a home is one of the largest financial investments most people make. Homeowners insurance helps protect that investment against a wide range of...

A Falling Tree Crushed Her Detached Garage. Her Policy Capped the Payout at $30,000.
Her detached garage and fence cost $52,000 to rebuild, but Coverage B capped the check at $30,000. Here is how the other structures limit really works.
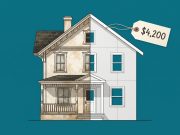
A Burst Pipe Cracked Agnieszka Nowak’s Original 1925 Plaster Ceiling. Her Policy Rebuilt It...
On a 1925 home, the functional replacement cost endorsement already attached to the policy settles damage with current materials, not the original lath-and-plaster, and the difference comes out of the homeowner's pocket.

Your ALE Coverage Covers Temporary Housing, But Most Rebuilds Outlast the 12-Month Clock
Her insurer paid for the temporary apartment, the higher restaurant bill, and the pet boarding for 11 months. By month 12 the rebuild was still six weeks out and the ALE clock had stopped.
The Compressor Died in August. Walter’s Insurer Never Sent an Adjuster, Because Mechanical Breakdown...
An air conditioning compressor died in August and Walter's homeowners insurer denied the claim outright. The reason is an exclusion most policyholders never read.