

When the Condo Board’s Deductible Becomes Your $15,000 Bill
A windstorm hit her condo building's roof, and the association's board legally passed the master policy's deductible straight to the owners. Here's why her insurance barely covered it.

You Turned Your Old House Into a Rental and Didn’t Tell Your Insurer. Your...
A Charlotte couple kept the homeowners policy on their old house after renting it to a family friend. Ten months later a kitchen fire caused $87,000 in damage and the insurer walked away.

A Wind Storm Tore Siding Off One Wall of Their Home. A Discontinued Color...
A wind storm tore vinyl siding off the south wall of a couple's Indianapolis home. The insurer authorized one wall. Their color had been discontinued. Indiana's matching law turned a $4,800 partial repair into a $19,200 full replacement.
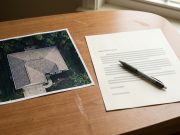
She Paid $16,400 for a New Roof. Her Nonrenewal Notice Cited a Photo Taken...
A homeowner's nonrenewal notice cited an aerial roof photo taken more than a year before she replaced the roof. Here is what these images can and cannot prove, and the dispute rights already on the books in several states.

Personal Property Sublimits: Why Your $250,000 Homeowners Policy Pays Only $1,500 for Stolen Jewelry
A burglary cleaned out $9,200 in jewelry from Lauren Castillo's bedroom dresser. Her $250,000 homeowners policy paid only $1,500 because of a sublimit she had never read.

Homeowners Insurance Doesn’t Cover Flooding
Sandra had $340,000 in homeowners coverage and three feet of water in her living room. Her insurer paid zero. The standard homeowners policy excludes flooding entirely, and most homeowners don't find out until after the loss.

Wind and Hail Percentage Deductibles: Why a $58,000 Roof Claim Can Leave You Paying...
Carmen Ortiz expected to pay her $2,500 homeowner deductible on a $58,000 hail roof claim. Her policy carried a 2% wind and hail deductible on her $420,000 dwelling limit, so her out-of-pocket was $8,400. Percentage deductibles for wind and hail are a separate line most homeowners never read.

Recoverable Depreciation: The Second Insurance Check Most Homeowners Never Claim
When a replacement cost policy pays a claim, the first check is short by the depreciation amount. That holdback is recoverable, but only if you finish the repair and send the final invoice. Most homeowners leave it on the table.

Your Insurer Called a Slow Leak ‘Gradual Seepage’ and Denied the Claim. Here’s How...
Homeowners policies cover sudden, accidental water damage but exclude gradual seepage that builds over time. The difference decides whether your claim is paid, and an adjuster can read the age of a leak in the walls.

His Mold Remediation Estimate Was $18,400. His Homeowners Insurer Paid $5,000.
Marcus discovered black mold spreading across his basement drywall after a slow pipe leak. His remediation estimate was $18,400. His insurer paid $5,000.